Navigating New CFPB Complaint Rules: What You Need to Know
The Consumer Financial Protection Bureau has implemented new rules for filing complaints, including two-factor authentication and changes to credit report dispute processes. Here’s how these changes might affect you and what steps you should take.
For many Americans, dealing with financial institutions can be a daunting task, especially when issues arise. Whether it’s a billing error, a fraudulent charge, or inaccuracies in your credit report, knowing how to effectively file a complaint is crucial. The Consumer Financial Protection Bureau (CFPB), an agency designed to protect consumers in the financial sector, has recently overhauled its complaint process. These new rules aim to streamline how complaints are handled, but they also introduce some complexities that could affect how consumers seek redress.
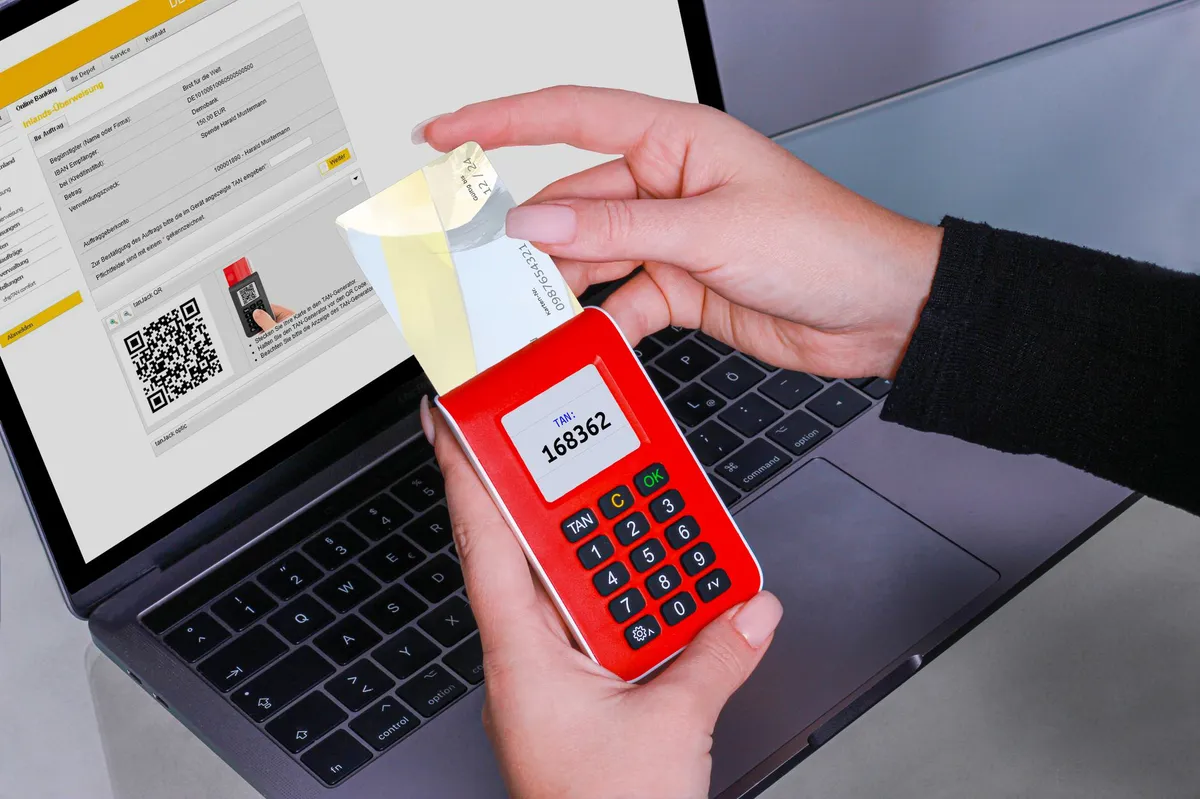
The most significant change involves the introduction of two-factor authentication for users creating online accounts to submit complaints. This means that consumers will now need to verify both their email address and phone number before proceeding. Additionally, if you need to dispute inaccurate information on your credit report, the CFPB now requires that you first address this issue directly with the credit reporting agencies—Equifax, Experian, and TransUnion—before bringing the matter to the CFPB. This shift is a response to an overwhelming number of complaints that surged from over 150,000 in 2019 to more than 5 million in 2025. While the CFPB believes these changes will help prioritize serious complaints, critics argue that they may create barriers for consumers seeking assistance.
Understanding the Role of the CFPB
The CFPB was established in 2011 in the wake of the financial crisis, with the mission of ensuring that consumers are treated fairly by financial institutions. The agency provides a platform for individuals to report issues they encounter with banks, credit card companies, mortgage lenders, and other financial service providers. When a complaint is filed, the CFPB forwards it to the relevant company, which is generally expected to respond within 15 days.
However, the agency is also tasked with managing a growing volume of complaints. The staggering increase in complaints over recent years has prompted the CFPB to focus more on those that require a substantive response. This means that not every complaint will receive the same level of attention, and the new rules are ostensibly designed to ensure that resources are allocated where they are most needed.
New Complaint Submission Process
Under the new rules, filing a complaint with the CFPB has become more structured:
- Two-Factor Authentication: Consumers must verify their identity through both email and phone before submitting a complaint.
- Direct Disputes Required: Before filing a complaint regarding inaccurate credit reporting, consumers must first file a dispute with the credit reporting agencies.
- Focus on Serious Complaints: The CFPB intends to prioritize complaints that warrant a substantive response, potentially leaving minor issues unresolved.
These changes, while intended to improve the efficiency of the complaint process, have raised concerns among consumer advocates. Many worry that requiring consumers to navigate multiple steps may deter them from seeking help altogether, particularly those who may already be facing financial hardships.
Potential Impacts on Consumers
The implications of these changes extend beyond merely altering how complaints are filed. For consumers, particularly those who are less financially literate, the new rules could create significant obstacles. For example, individuals who discover fraudulent activity on their credit report may feel overwhelmed by the prospect of having to dispute the error with the reporting agencies first, especially if they are unfamiliar with the process.
Furthermore, if consumers encounter difficulties in resolving their disputes with credit reporting companies, they may find themselves with no clear recourse. As noted by the National Consumer Law Center, the new rules could dissuade people from disputing credit report errors, which may lead to long-term negative impacts on their credit scores and overall financial health. This is particularly concerning given that credit scores play a crucial role in determining loan eligibility and interest rates.
Alternative Avenues for Resolving Complaints
Before escalating issues to the CFPB or other agencies, consumers should first attempt to resolve complaints directly with the financial service provider. Here are some steps to consider:
- Contact the Provider: Most companies have customer service departments designed to address complaints. Reaching out directly can often lead to a quicker resolution.
- File a Dispute: For errors on your credit report, file a dispute with each credit reporting agency directly. You can find the dispute links on the homepages of Equifax, Experian, and TransUnion.
- Seek Mediation: If you’re still dissatisfied after contacting the provider, consider involving your state’s consumer protection office, which can mediate disputes.
- Use Consumer Advocacy Groups: Organizations like the Better Business Bureau or Elliott Advocacy can help you navigate the complaint process and may even advocate on your behalf.
Financial Professionals: A Valuable Resource
In some cases, the ramifications of financial disputes can extend beyond immediate concerns. Consulting with a financial professional can provide insights into how these issues may affect your overall financial health. A financial advisor can help you understand potential impacts on your credit score, budget, and future borrowing capacity. This proactive step can empower you to make informed decisions moving forward.
Key Takeaways
- The CFPB has introduced new rules requiring two-factor authentication for online complaints.
- Consumers must file disputes with credit reporting agencies before escalating issues to the CFPB.
- Critics argue the new rules may create barriers for consumers seeking help.
- Contact financial service providers directly before involving third parties.
- Consider consulting a financial professional for broader financial implications.
Frequently Asked Questions
What should I do if I have a complaint against a financial institution?
If you have a complaint against a financial institution, your first step should be to contact them directly. Most companies have customer service protocols in place to address disputes. If that doesn’t resolve the issue, you can file a complaint with the CFPB, but remember that you’ll need to go through the two-factor authentication process and may need to document any previous attempts to resolve the issue.
How do I dispute an error on my credit report?
To dispute an error on your credit report, you need to file a dispute directly with the credit reporting agency where the error appears. You can do this by visiting the websites of Equifax, Experian, or TransUnion. Each agency has an online process for submitting disputes, and they are required by law to investigate your claim and respond within a specified timeframe.
Why were these new rules implemented by the CFPB?
The new rules were implemented primarily to manage the surge in complaints received by the CFPB over recent years. By requiring two-factor authentication and mandating that consumers first dispute inaccuracies with credit reporting agencies, the CFPB aims to streamline the complaint process and focus on more serious complaints that require a substantive response.
Are there other organizations that can help with financial complaints?
Yes, aside from the CFPB, there are several organizations that can assist with financial complaints. State consumer protection offices can mediate disputes, while the Better Business Bureau can forward complaints to businesses. Additionally, advocacy groups like Elliott Advocacy provide assistance for free, though they may publish your case to help inform others.
Disclaimer: This content is educational and not financial advice.
Comments
Why Your Scrapbook Should Matter as Much as Your Checkbook
Prioritizing experiences over savings can create lasting memories with loved ones. Wealth adviser Dryden Pence shares how to intentionally spend your resources on what truly matters.
Related articles
Popular in Personal Loans
- Hardee's Franchisee Files for Chapter 11 Amid Financial Turmoil
- The Hidden Costs of SUVs: Understanding the 'SUV Tax' and Its Impact on Your Wealth
- Spectrum's Workforce Changes Amid Customer Losses: What It Means for You
- How Immigration Policy Changes are Impacting Care Worker Shortages and Family Costs
- Unlocking Wealth: The Potential of Trump Accounts for American Families