The Role of AI in Personal Finance: When to Trust Technology and When to Seek Human Advice
As AI technology becomes increasingly integrated into personal finance, understanding its strengths and limitations is crucial. This article explores how to effectively combine AI tools with the invaluable insights of human financial advisors.
In today's fast-paced digital age, artificial intelligence (AI) is radically changing how we approach personal finance. From budgeting apps to robo-advisors, these tools are becoming an integral part of our financial lives. A recent survey by NerdWallet revealed that a staggering 43% of Americans have turned to AI for assistance with financial planning. While this trend is encouraging, it's essential to understand the limitations of AI and recognize when human expertise is irreplaceable.
AI can track spending, organize expenses, and even alert us to unusual account activity, making it a powerful ally in managing our finances. However, it lacks the ability to offer personalized guidance tailored to individual circumstances. This distinction is critical, as overlooking it can result in costly mistakes. By understanding the strengths and weaknesses of AI in finance, you can leverage its capabilities while ensuring that you don't miss out on the nuanced insights that only a human advisor can provide.
The Promise of AI in Financial Management
AI serves as an invaluable assistant for a variety of financial tasks, especially in areas that benefit from consistency and data analysis. Here are some ways AI can enhance your financial management:
- Budgeting Assistance: AI can help you build and manage your first budget by categorizing expenses and tracking spending patterns.
- Financial Education: AI platforms can explain complex concepts like compound interest or retirement account types in straightforward language.
- Automated Alerts: Setting reminders for bill payments or flagging unusual spending can help you maintain better control over your finances.
- Data-Driven Insights: AI excels at performing repetitive tasks that require speed and accuracy, ensuring you stay organized.
For those who may have never consulted a financial professional, AI democratizes access to essential financial knowledge. It allows users to learn the fundamentals of investing and retirement planning from the comfort of their own homes. This newfound accessibility can encourage individuals to engage more actively with their financial health.
The Pitfalls of Overreliance on AI
While AI can be an excellent educational tool, a significant concern arises when users start treating AI-generated recommendations as tailored financial advice. Most AI systems operate on algorithms that provide generalized answers based on data inputs, often lacking the personal context necessary for effective financial planning.
For example, consider two individuals who are both 58 years old, each with $900,000 saved in a 401(k) and a paid-off home, both hoping to retire at 65. On the surface, their financial situations appear identical. However, one has a secure government pension, while the other is self-employed and expects substantial healthcare costs due to a spouse's chronic illness. These personal circumstances significantly influence their financial strategies, but an AI tool would struggle to provide the nuanced advice necessary for each case.
The Emotional Component of Financial Decisions
Another critical aspect that AI cannot replicate is the emotional intelligence required in financial decision-making. Many financial decisions are driven by feelings, such as fear during market downturns or overconfidence during bull markets. These emotional responses can lead to costly mistakes, like panic-selling investments or making impulsive purchases.
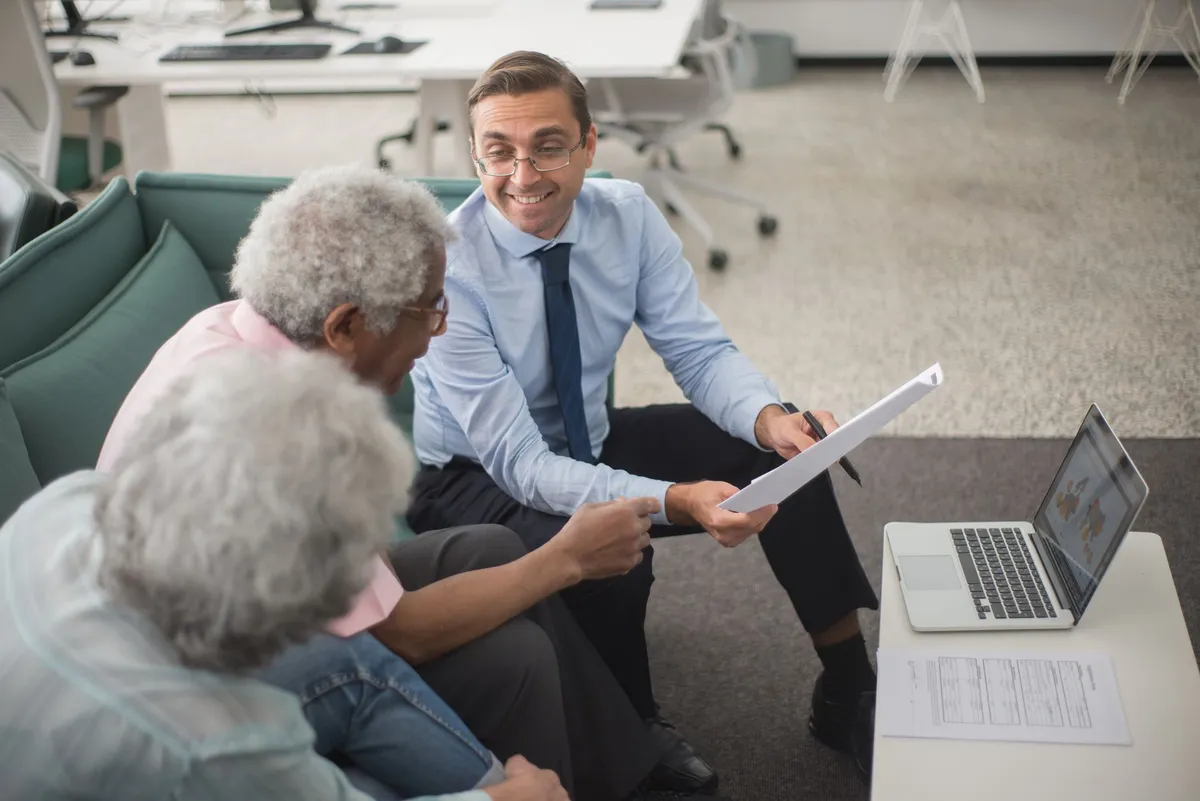
A human financial advisor can interpret emotional cues and guide clients through challenging decisions. For instance, during volatile market conditions, an advisor can reassure clients and help them focus on long-term goals instead of reacting impulsively to immediate market changes. AI lacks this ability to understand the emotional factors influencing a decision, which can be detrimental in high-stakes situations.
Combining AI with Human Expertise
Rather than viewing AI and human advisors as mutually exclusive, the most effective approach is to leverage both. Here are some practical guidelines for using AI in personal finance:
- Use AI for Routine Tasks: Let AI handle budgeting, tracking expenses, and automating reminders. This frees up time for more complex financial discussions.
- Consult Experts for Major Decisions: For significant financial moves—like retiring, signing legal documents, or making large investments—seek advice from a qualified professional who understands your complete financial picture.
- Educate Yourself: Use AI to learn about financial concepts, but don't hesitate to ask a professional for clarification or personalized advice.
- Stay Alert to AI's Limitations: Be mindful that AI-generated recommendations can be generic. Always consider your unique circumstances before acting on its advice.
By combining the efficiency of AI with the personalized insights of a financial advisor, you can make more informed decisions and improve your overall financial health.
Key Takeaways
- AI can assist with budgeting, organizing expenses, and financial education but lacks personalized insight.
- Emotional factors significantly influence financial decisions, which AI cannot adequately address.
- Effective financial management involves using AI for routine tasks while seeking human expertise for significant decisions.
- Understand the limitations of AI to avoid costly mistakes stemming from generic advice.
Frequently Asked Questions
How can I start using AI for my personal finances?
To begin using AI for personal finance, explore budgeting apps or robo-advisors. Many platforms offer free trials, allowing you to test their capabilities. Start by inputting your financial data and using the features that can help you track spending, set budgets, or learn about investment options. Always remember to supplement AI insights with human advice for significant decisions.
What are the risks of relying solely on AI for financial advice?
The primary risk of relying solely on AI is that it lacks the personal context necessary for effective financial planning. AI cannot account for individual circumstances such as family obligations, health issues, or life changes that may affect financial decisions. This can lead to misguided advice that does not align with your unique situation, potentially resulting in costly mistakes.
When should I consult a financial advisor instead of using AI?
Consult a financial advisor when making significant financial decisions, such as retirement planning, estate planning, or major investments. These decisions often require a nuanced understanding of your unique circumstances and long-term goals that AI cannot provide. A professional can offer tailored advice and help you navigate complex financial situations with emotional intelligence.
Is AI capable of learning from my financial behavior over time?
Yes, many AI-driven financial tools use machine learning algorithms to analyze your financial behavior over time. This allows them to provide more personalized recommendations based on your spending habits, savings patterns, and investment preferences. However, while AI can adapt to your behavior, it still lacks the human touch needed for contextual advice based on life changes.
This article is for educational purposes only and does not constitute financial advice.
Comments
Small Changes, Big Impact: Enhancing Client Relationships in Finance
Discover how minor adjustments in your sales process can significantly improve client relationships and retirement planning outcomes. This article explores actionable strategies for financial advisers to better serve their clients.
Related articles
Popular in Personal Loans
- Hardee's Franchisee Files for Chapter 11 Amid Financial Turmoil
- The Hidden Costs of SUVs: Understanding the 'SUV Tax' and Its Impact on Your Wealth
- Spectrum's Workforce Changes Amid Customer Losses: What It Means for You
- How Immigration Policy Changes are Impacting Care Worker Shortages and Family Costs
- Unlocking Wealth: The Potential of Trump Accounts for American Families