Emergency Savings Shortfall: A Growing Concern for American Households
With a significant number of American workers lacking sufficient emergency savings, financial experts warn of the dangers this poses to households. Learn about the current state of emergency funds, legislative efforts to improve savings, and actionable steps to secure your financial future.
In an era characterized by economic uncertainty and rising living costs, the vital importance of emergency savings has never been clearer. Yet, a recent survey reveals that more than half of American workers — a staggering 55% — lack adequate funds to cover a mere $500 emergency expense. This alarming statistic underscores a broader financial crisis, one where even those with jobs and steady paychecks are feeling the pinch. Personal finance expert Suze Orman, co-founder of SecureSave, emphasizes that we are facing unprecedented danger, as many households struggle to meet essential expenses.
The need for a robust emergency savings fund cannot be overstated. These funds act as a financial safety net, providing critical support during unforeseen circumstances like medical emergencies, car repairs, or job loss. However, data shows that the majority of Americans are falling short. The Federal Reserve’s 2025 report indicates that only 63% of adults could cover a $400 emergency expense, a figure that has stagnated over the past few years. As inflation continues to rise and household debt balloons, the urgency for effective saving solutions is becoming more pronounced.
Understanding the Financial Landscape
The backdrop of this emergency savings shortfall is one of increasing financial strain for American households. Inflation rates, though moderating, remain above the Federal Reserve's target of 2%, with the latest consumer price index showing an annual inflation rate of 3.4% as of July. This has resulted in soaring prices for essential goods and services, with average gas prices exceeding $4 per gallon, a record high for this time of year. Compounding these issues, total household debt has climbed to an eye-watering $18.8 trillion, up $4.6 trillion since the end of 2019, reflecting the financial burdens many families are shouldering.
The Debt Dilemma
The increase in household debt is troubling, particularly as auto loan balances have surged to $1.71 trillion and credit card balances have reached $1.26 trillion, nearing an all-time high. This rising debt, coupled with high interest rates, places further pressure on already strained budgets. Notably, new delinquencies for both auto loans and credit cards have also spiked, signaling that many consumers are struggling to keep up with their financial obligations. This environment makes it even more critical for individuals to prioritize building emergency savings.
The Impact of Inflation and Hardship Withdrawals
As inflation continues to erode purchasing power, many Americans are resorting to hardship withdrawals from their retirement savings. According to Vanguard, the share of defined contribution plan participants taking these withdrawals has nearly tripled from 2% in 2020 to 6% in 2025. Hardship withdrawals allow individuals to access their retirement funds for emergencies, educational expenses, and other qualifying needs. However, this trend raises concerns about the long-term financial health of retirees, as it effectively drains funds that are intended for future security.
The Role of Legislation
The passage of the Secure 2.0 Act in 2022 has introduced measures aimed at improving emergency savings options for employees. This law enables participants in defined contribution plans to withdraw up to $1,000 per calendar year for emergencies without incurring penalties. However, this amount must typically be repaid before additional withdrawals can be made within the subsequent three years. Furthermore, the legislation permits the automatic enrollment of workers into pension-linked emergency savings accounts (PLESAs), allowing for contributions of up to $2,600 in 2026, which can be withdrawn without tax penalties.
Current Offerings and Employer Initiatives
Despite these legislative advancements, the uptake of emergency savings plans remains low. A recent Vanguard analysis revealed that only 4% of 401(k) plans currently offer the $1,000 emergency withdrawals permitted by the Secure 2.0 Act. The slow implementation of PLESAs is attributed to delays in regulatory guidance and the need for record keepers to adapt their systems. Recently, T. Rowe Price became the first company to launch pension-linked emergency savings accounts, indicating a potential shift in the market.
Employer Benefits
For employers, providing access to emergency savings accounts can be a cost-effective benefit that enhances employee financial well-being. These programs often involve simple payroll deductions, and employers may choose to contribute to employees' savings. Research indicates that when employers offer such benefits, participation rates are notably high. As Shai Akabas from the Bipartisan Policy Center notes, there has been a significant increase in employers adopting emergency savings plans, drawing attention to the urgent need for these financial tools.
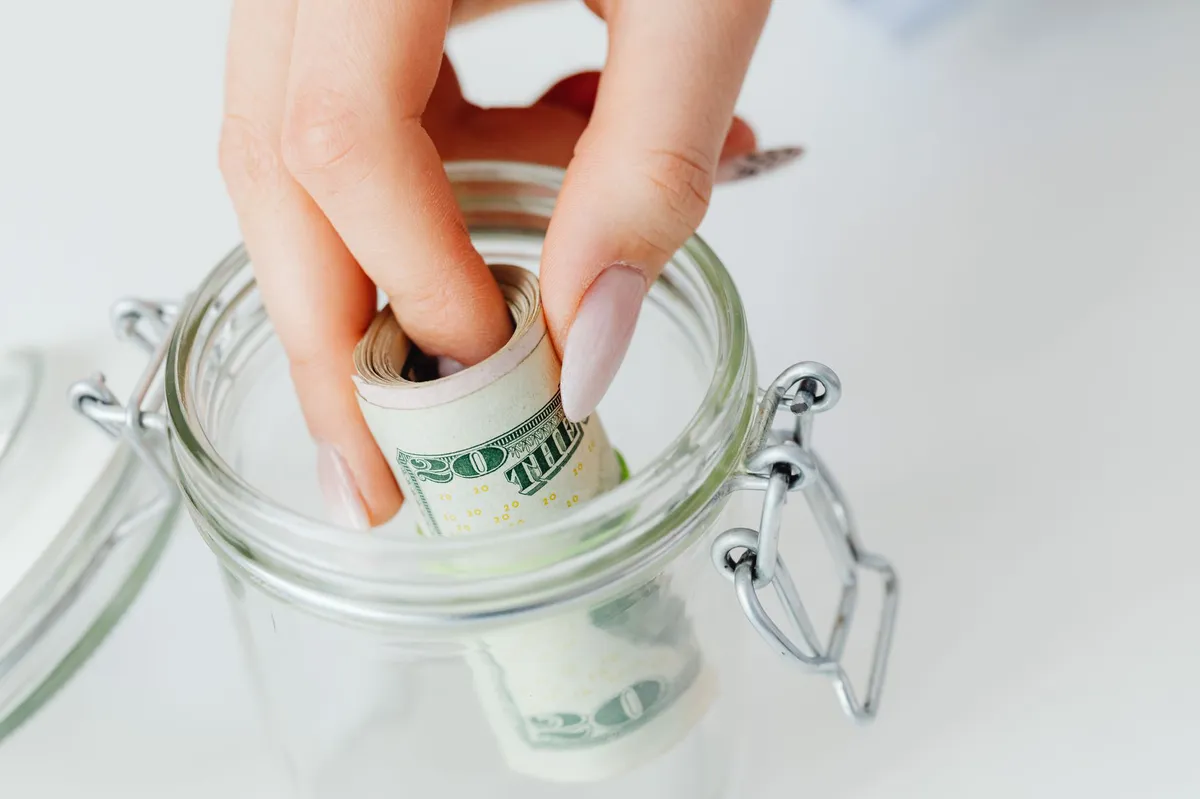
Future Directions for Emergency Savings
Looking ahead, policymakers are exploring additional legislative options to bolster emergency savings initiatives. One such proposal is the Emergency Savings Enhancement Act, which aims to increase the maximum annual contribution limit for PLESAs to $5,000 and expand participation eligibility to highly compensated employees. This could enhance access to emergency savings for a wider range of workers and address the growing financial insecurity facing many American households.
Encouraging a Savings Culture
To combat the emergency savings crisis, both individuals and employers must prioritize creating a culture of saving. Financial education and awareness are crucial components in helping workers understand the importance of emergency funds. Simple steps such as setting up direct deposits into savings accounts, automating contributions, and leveraging employer-sponsored savings programs can help individuals build their financial safety nets. By fostering a proactive approach to savings, we can mitigate the risks associated with financial emergencies and ensure greater stability for American families.
Key Takeaways
- 55% of workers lack adequate savings to cover a $500 emergency.
- Household debt has reached $18.8 trillion, compounding financial stress.
- The Secure 2.0 Act offers new options for accessing emergency savings.
- Employers play a critical role in providing savings benefits to enhance employee financial health.
- Future legislation may expand access to emergency savings accounts.
Frequently Asked Questions
What is an emergency savings fund and why is it important?
An emergency savings fund is a dedicated pool of money set aside to cover unexpected expenses, such as medical bills, car repairs, or job loss. It serves as a financial safety net, helping individuals avoid going into debt or relying on credit cards during crises. Experts recommend having three to six months' worth of living expenses saved in an emergency fund to ensure adequate protection against financial shocks.
How can I start building an emergency savings fund?
To begin building an emergency savings fund, start by setting a realistic savings goal based on your monthly expenses. Open a separate savings account to keep your emergency funds distinct from your regular spending money. Automate your savings by setting up direct deposits from your paycheck into this account. Aim to contribute a small percentage of your income each month and gradually increase the amount as your financial situation improves.
What are hardship withdrawals and how do they affect my retirement savings?
Hardship withdrawals allow individuals to access funds from their retirement accounts without penalties for qualifying needs, such as medical emergencies or significant financial burdens. While these withdrawals can provide immediate relief, they ultimately reduce the amount available for retirement, potentially jeopardizing long-term financial security. It's crucial to consider the long-term implications of withdrawing from retirement savings and to explore other options before opting for a hardship withdrawal.
What role do employers play in emergency savings?
Employers can significantly impact their employees' financial well-being by offering emergency savings accounts and other financial wellness programs. By facilitating payroll deductions and possibly contributing to employee savings, employers can help workers build their emergency funds more effectively. This not only enhances employee satisfaction and retention but also fosters a more financially secure workforce.
This content is educational and not financial advice.
Comments
How a 58-Year-Old Engineer Built a $1 Million Fortune Through Stocks and Real Estate
Discover the inspiring journey of a 58-year-old engineer who achieved financial independence through smart investing in stocks and real estate. Learn key lessons that could help you on your path to wealth.
Related articles
Popular in Personal Loans
- Hardee's Franchisee Files for Chapter 11 Amid Financial Turmoil
- The Hidden Costs of SUVs: Understanding the 'SUV Tax' and Its Impact on Your Wealth
- Spectrum's Workforce Changes Amid Customer Losses: What It Means for You
- How Immigration Policy Changes are Impacting Care Worker Shortages and Family Costs
- Unlocking Wealth: The Potential of Trump Accounts for American Families