Summer Financial Planning: Six Crucial Moves to Make Now
Don't wait for December to assess your financial health. Discover six essential financial moves to make this summer that will set you up for success as the year ends.
As summer unfolds, many Americans find themselves enjoying vacations, barbecues, and leisurely days by the pool. But amidst the bliss of the season lies an often-overlooked opportunity for financial planning. Traditionally, December is seen as the time to assess your financial standing and make crucial decisions. However, waiting until year-end can lead to rushed decisions, missed opportunities, and unnecessary stress. By taking a proactive approach in the summer, you can make informed adjustments that will benefit your financial health and peace of mind as the year progresses.
Now is the perfect time to dive into your financial strategy with six key moves that will not only help you capitalize on the current market conditions but also ensure that your financial decisions align with your long-term goals. Let’s explore these essential actions that can significantly impact your financial outcome by the end of the year.
1. Rebalance Your Investment Portfolio
Investment portfolios require regular attention to ensure they reflect your financial goals and risk tolerance. Over time, market fluctuations can cause your asset allocation to drift from your original plan. For instance, if your portfolio was initially balanced between 60% equities and 40% bonds, strong performance in the stock market could shift that to 70% equities, making your portfolio riskier than intended.
A mid-summer review can help you:
- Identify asset classes that have drifted from target allocations.
- Determine whether new contributions should be directed toward underperforming investments.
- Review the location of assets across taxable and tax-advantaged accounts for tax efficiency.
Consider this illustration: if you hold high-yield bonds in a taxable account, you might want to shift them to a tax-deferred retirement account to maximize returns.
2. Assess Your Retirement Contributions
Many individuals set their retirement contribution rates at the start of the year and forget about them. However, changes in income due to raises or bonuses could impact your retirement savings goals. If your salary increases but your contribution percentage remains the same, you may not be saving enough for retirement.
Review your contribution rates now, allowing time to make gradual adjustments rather than facing a large increase in November or December. Additionally, consider whether a mix of traditional and Roth contributions is appropriate for your current tax situation and future income expectations.
For example, if you expect to be in a higher tax bracket during retirement, prioritizing Roth contributions now allows for tax-free withdrawals later.
3. Run a Tax Projection
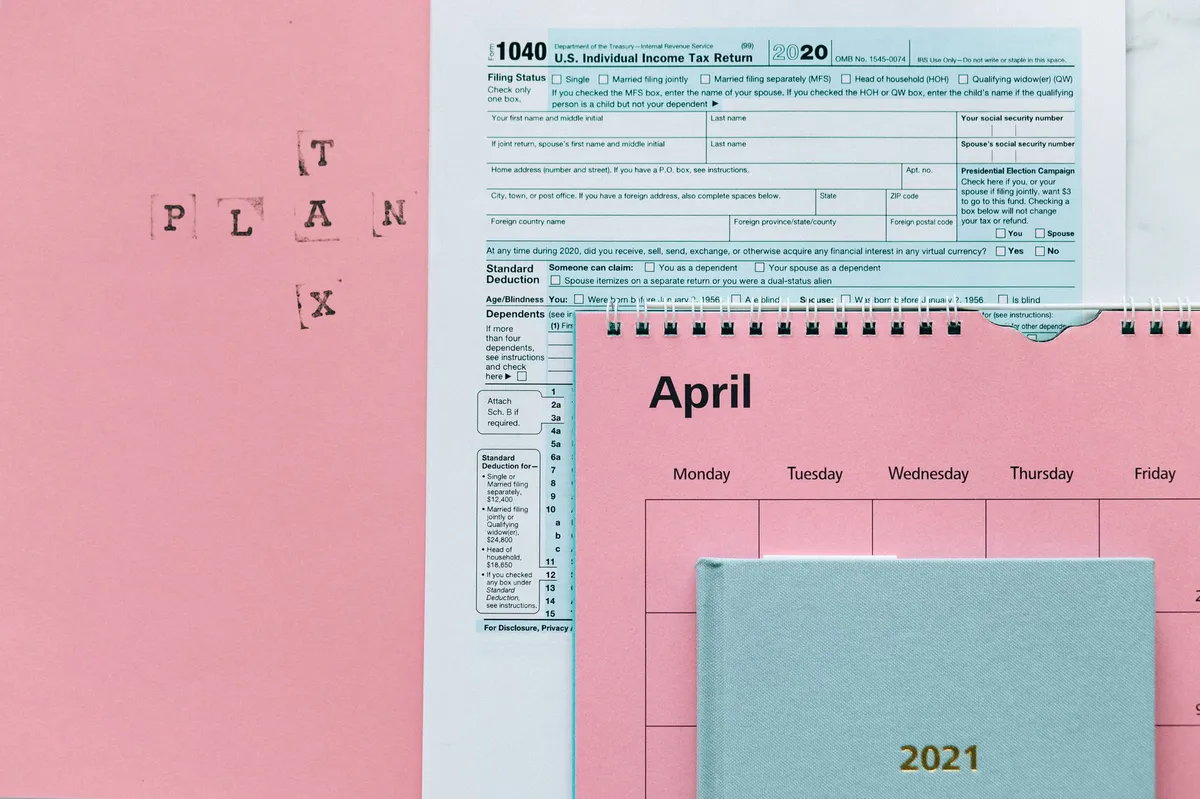
As summer progresses, your financial picture becomes clearer. This is an ideal time to run a tax projection to assess your current situation and make necessary adjustments to tax withholding or estimated payments. By analyzing your income from wages, bonuses, and investment gains, you can determine if you need to increase or decrease your withholding.
Moreover, proactive tax planning can uncover valuable opportunities:
- Consider Roth conversions to manage tax brackets.
- Utilize losses from investments to offset capital gains.
- Plan the timing of stock-option exercises to optimize tax outcomes.
This forward-thinking approach not only aims to reduce your tax bill but also aligns your tax strategy with your broader financial objectives.
4. Strategically Manage Cash and Debt
Cash management is critical for ensuring you have liquidity for upcoming expenses without relying on credit. Evaluate your cash reserves to determine if you have enough set aside for taxes, travel, or home improvements. If you have excess cash that isn't earning a competitive rate, consider investing it to achieve better returns.
On the flip side, assess your debts. For those with variable-rate loans, understanding how interest fluctuations affect cash flow is crucial. For instance, if you plan to make a significant purchase, consider how this new debt will impact your overall financial strategy.
5. Prepare for Employee Benefit Elections
Open enrollment periods can create a rush to make important benefit decisions. Instead of waiting until the end of the year, use the summer to evaluate your health, life, and disability insurance needs. Have there been major life changes such as a marriage, divorce, or the birth of a child that necessitate a review of your coverage?
Additionally, if you have access to a Health Savings Account (HSA), assess your contribution levels and how they fit within your broader financial plan. Executives should also review stock options and other compensation benefits to ensure they make informed decisions before deadlines.
6. Review and Update Estate Planning Documents
Estate planning is often a task that gets postponed, but summer is an excellent time to review your wills, trusts, and beneficiary designations. Major life events such as births, deaths, or changes in wealth can necessitate updates to your estate plan. Ensure that your documents reflect your current wishes and circumstances to avoid complications in the future.
For families considering significant gifts, begin planning early to accommodate valuation assessments and legal requirements. Remember, estate planning goes beyond taxes; it’s about making sure your assets are distributed according to your wishes and that the right individuals have the authority to act on your behalf in emergencies.
Key Takeaways
- Rebalance your portfolio to align with your risk profile and investment goals.
- Assess retirement contributions to ensure you’re on track for your savings goals.
- Run a tax projection to identify strategies for tax efficiency.
- Manage cash and debt to optimize liquidity and minimize reliance on credit.
- Review employee benefits early to make informed decisions.
- Update estate planning documents to reflect life changes and intentions.
Frequently Asked Questions
Why should I rebalance my investment portfolio now instead of waiting until December?
Rebalancing now allows you to make informed decisions based on current market conditions rather than waiting until year-end when you might feel rushed. By addressing any drift in your asset allocation during the summer, you can ensure that your portfolio remains aligned with your long-term goals and risk tolerance.
How can I determine if I need to increase my retirement contributions?
First, review your current contribution rate in relation to your income and savings goals. If you've had a salary increase or other changes in your financial situation, calculate whether your current contributions will enable you to meet your retirement objectives. If not, consider making adjustments now to avoid a larger increase later in the year.
What are some tax strategies I should consider during my summer review?
During your summer financial review, consider strategies such as Roth conversions, utilizing investment losses to offset gains, and timing stock-option exercises to optimize your tax situation. This proactive approach allows you to make well-informed decisions that can support your overall financial goals.
When should I update my estate planning documents?
It's advisable to review your estate planning documents whenever significant life events occur, such as marriage, divorce, or the birth of a child. Additionally, a general review every few years can help ensure that your wishes and circumstances are accurately reflected in your estate plan.
This content is educational and not financial advice.
Comments
Understanding the Shifting Landscape of the U.S. Economy: K, C, and Beyond
As signs of economic recovery emerge, the U.S. economy is transitioning from a K-shaped divide to a more inclusive model. This article explores the implications of this shift for various income groups and what it means for American households.
Related articles
Popular in Personal Loans
- Hardee's Franchisee Files for Chapter 11 Amid Financial Turmoil
- The Hidden Costs of SUVs: Understanding the 'SUV Tax' and Its Impact on Your Wealth
- Spectrum's Workforce Changes Amid Customer Losses: What It Means for You
- How Immigration Policy Changes are Impacting Care Worker Shortages and Family Costs
- Unlocking Wealth: The Potential of Trump Accounts for American Families