Navigating U.S. Tax Obligations as an Expat: What Young Americans Need to Know
For young Americans living abroad, understanding U.S. tax obligations is crucial. This article breaks down key tax considerations for expats, including filing requirements, exclusions, and credits.
As more young Americans venture overseas for study, work, or adventure, many are surprised to discover that their U.S. tax obligations don’t end when they set foot outside the country. For those considering making a temporary or permanent move abroad, navigating the complexities of international tax law can add a layer of stress to an already exciting life change. Understanding these obligations is not just a matter of compliance; it's essential for maintaining financial health and avoiding hefty penalties.
Erin Collins, the leader of the Taxpayer Advocate Service (TAS), highlights that tax issues faced by Americans abroad rank among the most pressing challenges for U.S. taxpayers. As U.S. citizens, expats must adhere to U.S. tax laws in addition to the laws of their adopted country. This dual responsibility can lead to confusion and potential pitfalls if not adequately addressed. For young expats like college student Reese Charron, who recently studied in Valencia, Spain, the reality of U.S. tax obligations can overshadow the joy of cultural immersion and new experiences.
Understanding Your U.S. Tax Responsibilities
U.S. citizens are required to report their worldwide income to the Internal Revenue Service (IRS), regardless of where they reside. This means that even if you are living and working in another country, your income must still be reported on your U.S. federal income tax return. However, this does not automatically equate to double taxation. Tax experts note that there are provisions in place that can help mitigate this issue.
Foreign Earned Income Exclusion
One of the most significant provisions available to expats is the Foreign Earned Income Exclusion (FEIE). For the 2026 tax year, eligible taxpayers may exclude up to $132,900 of foreign earned income from their U.S. federal income taxes. To qualify for the FEIE, you must meet certain criteria established by the IRS:
- You must be a "bona fide resident" of a foreign country for an uninterrupted period that includes an entire tax year.
- Alternatively, you may qualify by being "physically present" in a foreign country for at least 330 full days during a 12-month period.
It's important to note that claiming the FEIE is not automatic; taxpayers must file a U.S. tax return to claim this exclusion.
Foreign Tax Credit: An Additional Option
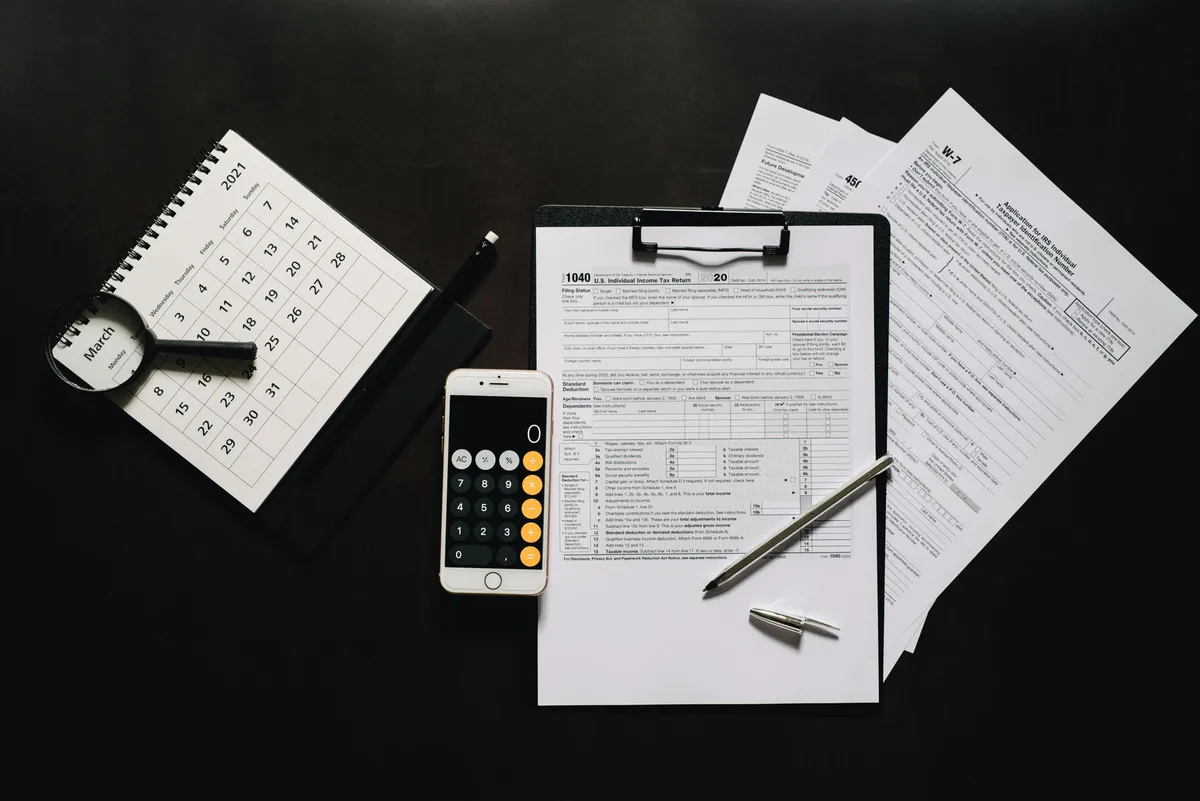
If you find yourself paying income taxes to the country where you reside, you might also be eligible for the Foreign Tax Credit (FTC). This credit allows you to either take a credit or an itemized deduction for taxes paid to a foreign government. However, if you choose to utilize the FEIE, you cannot also claim the FTC on the same income. This decision could have significant financial implications, so it's vital to assess your situation carefully.
Filing Extensions for Expats
U.S. citizens living abroad benefit from an automatic two-month extension to file their federal income tax return and pay any owed taxes, allowing them until June 15 for submission. However, it’s important to remember that interest on unpaid taxes typically accrues from the original due date of April 15. This extension can provide much-needed breathing room for expats, but it’s still essential to meet all reporting obligations.
Reporting Foreign Financial Accounts
In addition to income tax considerations, expats must also stay vigilant regarding reporting requirements for foreign financial accounts. Opening a bank account in your new country can trigger reporting obligations you may not have encountered in the U.S. For instance, if the combined value of your foreign financial accounts exceeds $10,000 at any point during the calendar year, you are required to file a Report of Foreign Bank and Financial Accounts (FBAR) with the Financial Crimes Enforcement Network (FinCEN).
FBAR Requirements
Filing the FBAR is crucial as it is a separate requirement from your federal tax return. The FBAR is due on April 15, with an automatic extension available until October 15 if needed. Failure to file can result in severe penalties, underscoring the importance of understanding these obligations. Additionally, if your foreign financial assets exceed specific thresholds, such as $200,000 at the end of the tax year or $300,000 at any time during the year, you must report these on a separate form with your federal tax return.
Planning Ahead: Consulting Professionals
Before making the leap to live and work abroad, it’s crucial for Americans to understand the financial landscape that awaits them. Tax rules vary widely from one country to another, so the obligations you face will depend on both your personal circumstances and the jurisdiction in which you reside. Consulting with tax professionals who are well-versed in both U.S. and international tax laws can provide invaluable guidance and help prevent unexpected tax issues down the road.
Considerations for Young Expats
For many young Americans, the excitement of living abroad often overshadows the complexities of tax compliance. As Charron noted, tax obligations were not on her radar while studying in Spain. However, as she navigates these new responsibilities, she realizes the importance of understanding how her financial situation may be impacted. Young expats should take proactive steps to educate themselves on their tax obligations, which may include:
- Researching local tax laws in their host country.
- Understanding U.S. tax laws applicable to expatriates.
- Seeking advice from tax professionals.
Key Takeaways
- U.S. citizens living abroad must report their worldwide income to the IRS.
- The Foreign Earned Income Exclusion allows eligible expats to exclude significant foreign income from U.S. taxes.
- Filing a Report of Foreign Bank and Financial Accounts (FBAR) is required for foreign accounts exceeding $10,000.
- Consulting a tax professional familiar with both U.S. and foreign tax laws is highly recommended.
Frequently Asked Questions
What happens if I fail to file my U.S. taxes while living abroad?
Failing to file your U.S. taxes as an expatriate can lead to significant penalties and interest on any unpaid taxes. The IRS has strict enforcement mechanisms in place for noncompliance, which can include fines and, in extreme cases, legal action. It's crucial to remain compliant to avoid these repercussions, even when living outside the country.
Can I claim both the Foreign Earned Income Exclusion and the Foreign Tax Credit?
No, you cannot claim both the Foreign Earned Income Exclusion and the Foreign Tax Credit on the same income. If you choose to utilize the FEIE, you must forgo the FTC for those earnings. Therefore, it's essential to evaluate your financial situation and tax obligations to determine the best approach for your circumstances.
Are there tax implications for selling property abroad?
Yes, selling property abroad can have tax implications for U.S. citizens. You may be subject to taxation in the country where the property is located, as well as potential U.S. tax obligations. The specifics will depend on the laws of the country where the property is located and your overall tax situation, making it advisable to consult a tax professional for guidance.
How can I ensure compliance with both U.S. and foreign tax laws?
To ensure compliance with both U.S. and foreign tax laws, it’s important to stay informed about the tax regulations in both jurisdictions. Consulting with tax professionals who specialize in expatriate tax issues can provide clarity and help you navigate the complexities of international tax obligations. Additionally, keeping detailed records of all income, expenses, and financial accounts is essential for accurate reporting.
Comments
Popular in Taxes
- Opportunity Zone 2.0: What Investors Need to Know for the 2027-2036 Designation
- Understanding State Capital Gains Tax Rates in 2026: A Comprehensive Guide for Investors
- Inheriting a House: Tax Implications and What You Should Know
- T-Mobile Plans and Rising Property Taxes: What You Need to Know
- Understanding the New IRS Gift Tax Exclusion for Trump Accounts