Why the 4% Rule Isn't Enough for Retirement Planning
The 4% rule is a popular guideline for retirement withdrawals, but it may not suit everyone's unique financial situation. Discover how personalized planning can safeguard your retirement.
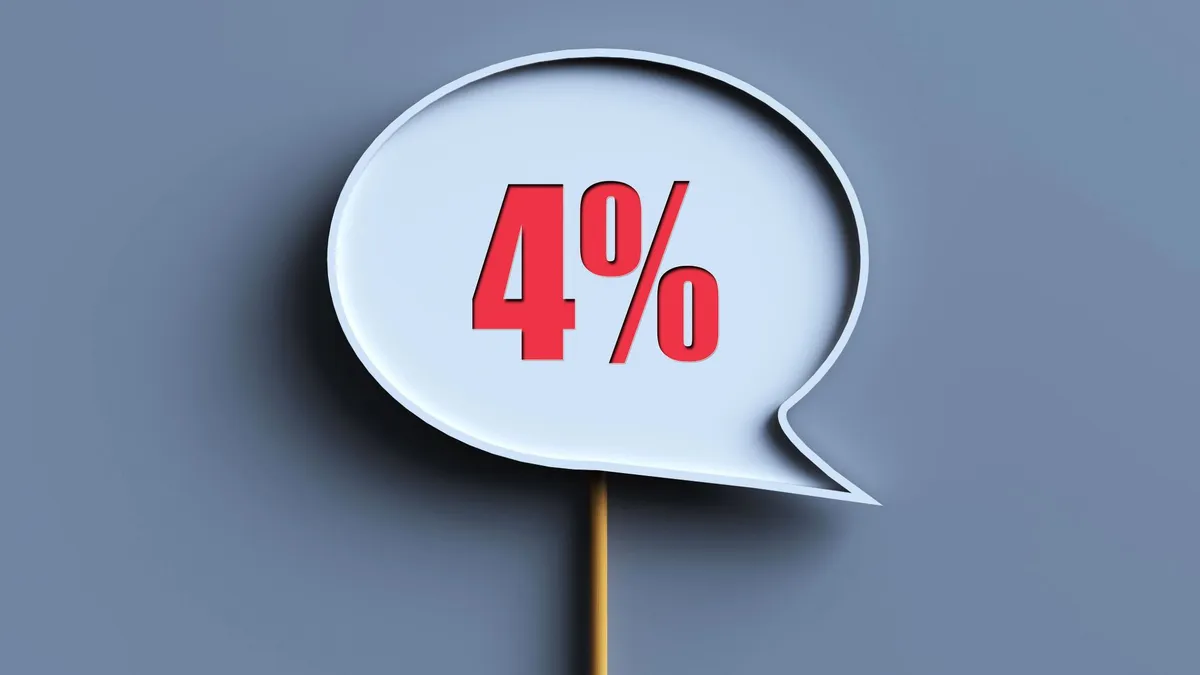
As you approach retirement, one of the burning questions that often arises is, "How much can I safely withdraw from my savings each year?" While many financial experts cite the 4% rule as a solid starting point, this simplistic guideline may not adequately address the complexities of individual retirement plans. In reality, the adequacy of this rule depends on a myriad of factors including market conditions, personal spending habits, health care costs, and even tax implications. Understanding these nuances is essential for creating a personalized plan that can sustain you throughout retirement.
The 4% rule suggests that retirees can withdraw 4% of their retirement portfolio in the first year, adjusting this amount for inflation in subsequent years. For example, a retiree with a $1 million nest egg could withdraw approximately $40,000 annually. While this rule can provide a rough estimate, it fails to account for the specific circumstances that can significantly impact an individual’s financial future.
The Limitations of the 4% Rule
The 4% rule is appealing primarily for its simplicity. However, retirement is anything but simple. Financial markets are volatile, healthcare expenses can soar, tax laws change, and personal circumstances evolve. Hence, a one-size-fits-all withdrawal rate may lead to financial strain, especially for those who retire early or face unforeseen expenses.
Understanding Individual Needs
To grasp why the 4% rule might not work universally, it’s crucial to understand the factors that influence a retiree's financial landscape:
- Retirement Duration: The length of retirement can drastically affect withdrawal needs. A retiree who plans for a 30-year retirement will need a different strategy than someone planning for just 15 years.
- Investment Strategy: The allocation of assets between stocks, bonds, and other investments can determine the risk and potential returns of your portfolio.
- Inflation: Over time, inflation erodes purchasing power, making it vital to consider how rising costs will impact your withdrawals.
- Tax Considerations: Different accounts (traditional IRAs, Roth IRAs, taxable accounts) carry various tax implications that can affect take-home income.
- Other Income Sources: Social Security, pensions, and rental income can supplement your withdrawals, thereby altering the amount needed from your investment portfolio.
Sequence of Returns Risk: A Hidden Danger
Another compelling reason to avoid a rigid adherence to the 4% rule is the concept of sequence of returns risk. This refers to the risk associated with the order in which investment returns occur. Two retirees may achieve the same average annual return over a 20-year period but have vastly different outcomes based on when gains and losses happen.
For instance, consider two retirees each starting with a $1 million portfolio, both withdrawing $40,000 annually. If one experiences strong market returns in the early years of retirement while the other faces a downturn, the latter may find their portfolio depleted much earlier. This is because withdrawing funds during a market decline forces them to sell investments at a loss, which can be devastating in the long term.
Mitigating Sequence of Returns Risk
While you cannot eliminate sequence of returns risk entirely, there are strategies to manage it:
- Maintain a Cash Reserve: Keeping a cash cushion can help cover near-term expenses without needing to sell investments during a downturn.
- Create Flexible Spending Rules: Establish guidelines for adjusting your withdrawals based on market performance to avoid depleting your assets during bad years.
- Systematic Rebalancing: Regularly rebalancing your portfolio can help ensure that you maintain your desired investment strategy and risk profile.
The Importance of Personalized Planning
Given the complexities of retirement planning, a personalized income strategy is essential. This involves consulting with a qualified financial adviser who can tailor a plan based on your specific needs and goals. A financial adviser can help you evaluate:
- Your projected retirement length and lifestyle needs.
- The most effective investment strategies that balance growth and security.
- The implications of taxes on your withdrawals across different types of accounts.
- How to coordinate Social Security benefits and other income sources to maximize your financial security.
Dynamic Withdrawal Strategies
Another approach to consider is a dynamic withdrawal strategy, which adjusts your withdrawal amounts based on market conditions and portfolio performance. This flexible approach allows retirees to increase withdrawals during strong market years while reducing them in difficult times, ultimately protecting the longevity of the portfolio.
Ongoing Guidance and Adaptation
Retirement planning should not be viewed as a one-time calculation. As markets fluctuate and personal circumstances evolve—whether due to changing health, tax laws, or lifestyle needs—your withdrawal strategy may require adjustments. Regular consultations with a financial planner can help ensure that you stay on track and adapt your strategy as needed.
Importantly, the value of financial advice lies not in predicting market movements but in helping retirees make informed, disciplined decisions based on a comprehensive, coordinated plan.
Key Takeaways
- The 4% rule is a useful guideline but may not be suitable for everyone.
- Factors such as retirement duration, investment strategy, and sequence of returns risk can greatly impact withdrawal plans.
- Personalized planning with a financial adviser can help tailor a strategy to meet individual needs.
- Dynamic withdrawal strategies allow for flexibility based on market performance.
- Ongoing financial guidance is essential for adapting to life changes and market fluctuations.
Frequently Asked Questions
What are some alternatives to the 4% rule?
Alternatives to the 4% rule include dynamic withdrawal strategies, which adjust based on market performance, or using a percentage of your portfolio that considers your specific needs, such as your life expectancy and lifestyle. You might also think about the bucket strategy, where assets are segmented into short-term, medium-term, and long-term buckets to manage withdrawals according to market conditions.
How can I assess my retirement spending needs?
To assess your retirement spending needs, create a detailed budget that accounts for essential expenses like housing, healthcare, food, and discretionary spending. Factor in potential costs that may rise with age, such as healthcare and long-term care. A financial planner can provide tools and insights to help you estimate these costs more accurately.
Is it worth it to hire a financial adviser for retirement planning?
Hiring a financial adviser can be invaluable for retirement planning. They bring expertise in market trends, investment strategies, and tax implications, which can help you develop a comprehensive, adaptable retirement plan. An adviser acts as a partner to navigate complex financial decisions and ensures your plan aligns with your long-term goals.
How often should I review my retirement plan?
It’s recommended that you review your retirement plan at least annually, or whenever there are significant life changes such as a job change, inheritance, or health issues. This regular checkup allows you to make necessary adjustments to your withdrawals, investments, and overall strategy in response to changing circumstances.
This article is intended for educational purposes and does not constitute individualized investment, tax, legal, or retirement advice.
Comments
Popular in Retirement
- Understanding Trump Accounts: A New Investment Opportunity for Kids
- The Impending Crisis: Social Security Reform and Its Economic Ripple Effects
- Navigating Long-Term Care Insurance: Flexible Alternatives for a Secure Future
- Balancing AI and Employee Loyalty: A Guide for Small Business Owners
- Navigating Retirement: Overcoming Doubts and Embracing Change