How Annuities Can Buffer Social Security Loss After a Spouse's Death
The death of a spouse often leads to a significant drop in Social Security benefits. Annuities can provide a financial safety net to help offset this loss. Explore how they work and what options are available.
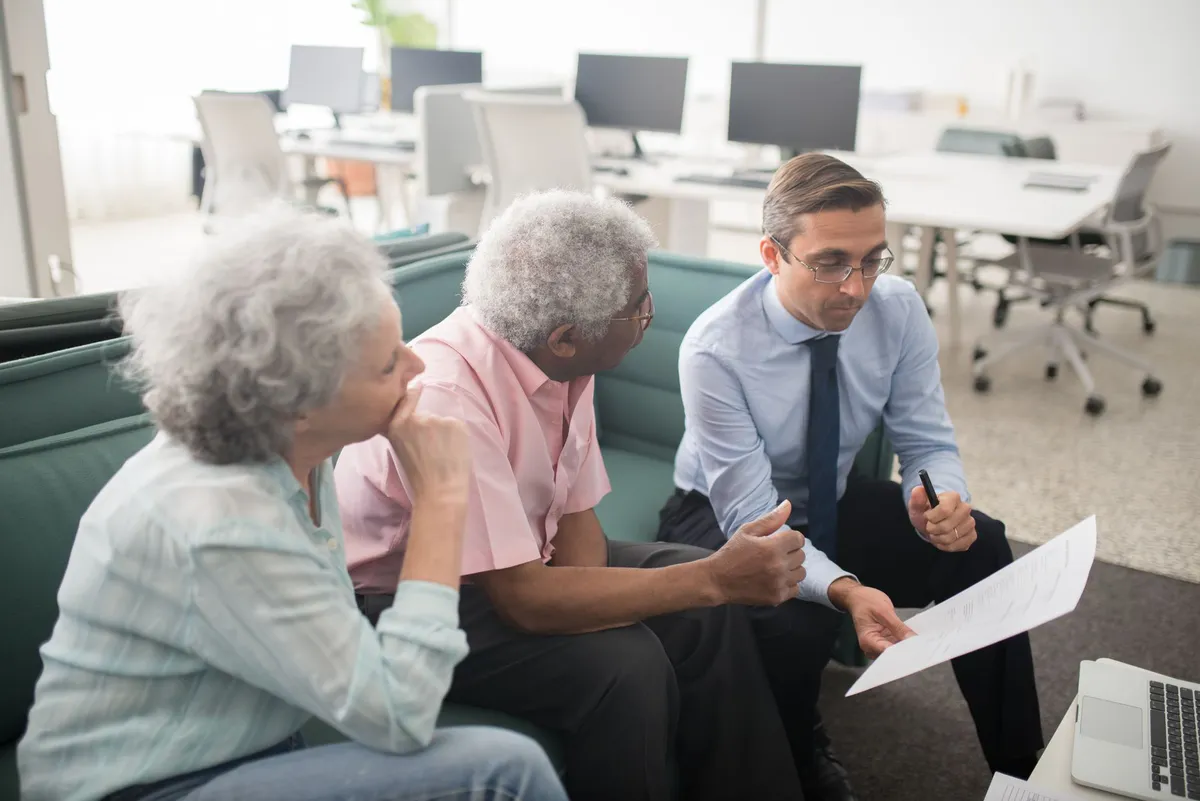
The death of a spouse can be one of the most emotionally devastating events in a person's life, but it can also have a profound financial impact, particularly when it comes to Social Security benefits. For many retired couples, Social Security serves as a critical lifeline, providing a substantial portion of their income. When one partner passes away, the surviving spouse may face a significant reduction in their monthly benefits, leading to an unexpected financial strain. However, annuities can play a crucial role in filling this income gap, offering a reliable source of funds during a challenging time.
Understanding how Social Security benefits work when a spouse dies is essential for effective financial planning. The Social Security Administration allows the surviving spouse to receive either their own benefit or the deceased spouse's benefit—whichever is higher. This can result in a dramatic drop in income, especially if both partners had been receiving substantial benefits. For example, if one spouse received $2,500 per month and the other $2,000, the survivor would continue to receive $2,500, resulting in a 44% drop in total benefits. If both were receiving $2,500, the income would plummet by 50%—a significant change that can leave many struggling to meet their financial obligations.
Understanding Social Security Benefits in Marriage
Social Security benefits are designed to provide financial support to individuals during retirement, but the system can be complex, especially for married couples. Here are some key points to consider:
- Survivor Benefits: The surviving spouse can access the deceased spouse's benefits, which can be equal to or more than their own.
- Eligibility Criteria: To qualify for survivor benefits, the deceased must have worked long enough to earn sufficient credits.
- Impact of Income on Benefits: The amount received can affect the overall financial stability of the surviving spouse.
Given these complexities, it's vital for couples to understand their options and plan accordingly to safeguard their financial future.
How Annuities Work as a Financial Safety Net
One effective way to mitigate the financial impact of losing a spouse is through annuities. An annuity is a financial product that provides a stream of income in exchange for a lump sum payment. There are various types of annuities, but two common options are:
Joint Lifetime Income Annuities
These annuities are designed to provide income for both spouses for as long as either partner lives. For instance, if a couple invests $200,000 into a joint lifetime income annuity, they can secure guaranteed monthly payments for life. If one spouse passes away, the survivor continues to receive the same payment amount, which helps cushion the loss of Social Security benefits.
Deferred Income Annuities
Deferred income annuities allow individuals to delay payments until a specified future date, often resulting in higher monthly income. For example, if the Jones couple, aged 67, deposits $200,000 in a deferred income annuity and decides to start payments at age 80, they could receive approximately $3,758.07 per month for as long as either is living. This income can significantly offset the potential loss of Social Security benefits.
The Importance of Planning for Longevity
With increasing life expectancies, planning for longevity is more crucial than ever. Annuities serve as a form of 'longevity insurance', ensuring that retirees do not outlive their savings. This is especially important when considering that many couples may rely heavily on Social Security benefits. The financial landscape can change dramatically with the death of a spouse, making it essential to have a plan in place.
Choosing the Right Annuity
When considering annuities, couples should weigh the pros and cons of each option. Factors to consider include:
- Immediate vs. Deferred: Immediate annuities start paying out right away, while deferred annuities allow for a later start date, often leading to larger payments.
- Tax Implications: Some of the income from annuities may be taxable, so it’s important to understand how this will affect your overall tax situation.
- Flexibility: Certain annuities, like indexed annuities with income riders, offer more flexible options for when to start receiving income.
Ultimately, the right choice depends on individual circumstances, such as health status, financial goals, and the current state of Social Security benefits.
Potential Drawbacks of Annuities
While annuities can provide a safety net, they also come with potential drawbacks that should be carefully considered:
Cash Surrender Value
Most traditional annuities do not have a cash surrender value, meaning that once you invest your money, it is exchanged for a stream of income—similar to a private pension. If you need access to your funds, this could present a problem.
Costs and Fees
Adding features like income riders can incur annual fees, typically around 1%, which can affect overall returns. It’s crucial to understand how these costs impact the growth of your investment.
Market Risks
Indexed annuities may provide some protection against market downturns, but they aren’t without risks. If the market performs poorly for an extended period, the cash value of the annuity could stagnate.
Key Takeaways
- When a spouse dies, Social Security benefits can significantly drop, impacting financial stability.
- Annuities can provide a reliable income stream to help offset the loss of Social Security benefits.
- Joint lifetime income annuities and deferred income annuities are popular options for couples.
- Careful planning is essential to navigate the complexities of Social Security and annuities.
- Potential drawbacks of annuities include lack of cash value, costs, and market risks.
Frequently Asked Questions
What are the benefits of purchasing an annuity?
Annuities provide a guaranteed income stream for a specified period or for life, which can be particularly beneficial in retirement. They help mitigate the risk of outliving your savings and can be tailored to meet individual financial needs, providing peace of mind during uncertain times.
How does the choice between immediate and deferred annuities impact my retirement planning?
Choosing between immediate and deferred annuities can significantly impact your retirement income. Immediate annuities provide quick access to funds but may yield lower monthly payments compared to deferred annuities, which allow for a larger lump sum to accumulate and potentially higher payouts in the future. Your choice should align with your cash flow needs and overall retirement strategy.
Are there tax implications associated with annuities?
Yes, annuities have specific tax implications. While the growth of the investment is tax-deferred, the income received may be partially taxable depending on the type of annuity and how it’s structured. It's essential to understand these implications and consult a tax advisor to optimize your tax strategy.
Can I access my annuity funds if I need them before the income starts?
Access to funds in an annuity typically depends on the type of annuity purchased. Traditional income annuities usually do not allow for early withdrawals, while some indexed annuities may offer cash value options. It's important to review the terms of your annuity contract to understand your options for accessing funds.
This content is educational, not financial advice.
Comments
Empowering Women to Take Control of Their Financial Future in Retirement
As women increasingly step into financial leadership roles, it's crucial to prepare for retirement well in advance. Here are six essential tips to ensure financial security and peace of mind during major life transitions.
Related articles
Popular in Retirement
- Understanding Trump Accounts: A New Investment Opportunity for Kids
- The Impending Crisis: Social Security Reform and Its Economic Ripple Effects
- Navigating Long-Term Care Insurance: Flexible Alternatives for a Secure Future
- Balancing AI and Employee Loyalty: A Guide for Small Business Owners
- Navigating Retirement: Overcoming Doubts and Embracing Change