Navigating College Savings: 529 Plans and Future Considerations
As college tuition continues to rise, understanding how to effectively save for education is more crucial than ever. This article delves into essential questions around 529 plans, excess funds, and the evolving necessity of a four-year degree.
As college tuition rates soar, with private institutions nearing $100,000 per year, many parents and grandparents are grappling with how to save effectively for their children's or grandchildren's education. The rising cost of education comes with complex questions about the best savings strategies, especially in light of a shifting job market and uncertainties surrounding the value of a four-year degree. This article explores critical considerations regarding 529 plans, the implications of excess funds, and whether a college education still holds its ground as a worthwhile investment.
Understanding 529 Plans: A Primer
529 plans are tax-advantaged savings accounts designed specifically for education expenses. They offer families the ability to save for college while benefiting from tax-free growth and tax-free withdrawals for qualified expenses. These plans come in two primary forms: prepaid tuition plans and education savings plans. The former allows families to pay for tuition at today’s rates, while the latter lets funds grow over time and can be used for a broader range of educational expenses.
When to Start Saving and How Much?
Financial experts suggest that the earlier you start saving, the better. Jonathan Codispoti, President at Legacy Wealth Strategies, recommends beginning at birth for maximum growth potential. The rationale is clear: the earlier you contribute to a 529 plan, the more time your funds have to grow through compounding interest.
Setting a Savings Goal
The cost of a four-year education is projected to be between $150,000 and $250,000 in 18 years. To fully fund an average public in-state university, you would need to save approximately $700 per month, or about $8,400 annually. For families who want to maximize their savings, utilizing superfunding strategies is advisable. This involves contributing up to $95,000 in a single year under the five-year gift tax averaging rule.
Prioritizing Retirement Savings
While it's crucial to save for college, experts advise parents first to prioritize their retirement savings. Michael Van Boening, a CFP at Mercer Advisors, emphasizes that you can borrow for college, but you cannot borrow for retirement. This means maxing out contributions to retirement accounts such as IRAs and 401(k)s before allocating funds to a 529 plan is a prudent strategy.
Excess 529 Funds: What to Do with Leftover Money
Having excess funds in a 529 plan is often viewed as a fortunate dilemma. Fortunately, there are several options available. Funds can be transferred to other family members, including siblings or even first cousins, or they can be saved for graduate school or vocational training.
New Opportunities Under SECURE 2.0
A significant update under the SECURE 2.0 legislation allows for the rollover of up to $35,000 from a 529 plan into a Roth IRA, provided certain conditions are met. For instance, the 529 account must have been open for at least 15 years, and the beneficiary must have earned income equal to or higher than the rollover amount. This flexibility alleviates the previous fear of incurring penalties for overfunding a 529 plan.
- Transfer funds to other family members
- Use for graduate or vocational education
- Rollover to a Roth IRA under SECURE 2.0
Future Changes to 529 Plans: What to Expect
As the landscape of education evolves, so too may the rules surrounding 529 plans. With a decline in college enrollment and rising awareness of alternative educational pathways, experts believe that lawmakers may lean towards increasing flexibility in how 529 funds can be utilized. Codispoti suggests that the trend thus far has favored expanding the use of 529 funds beyond traditional education, and this could continue.
The Impact of AI and Job Market Trends
The advent of artificial intelligence (AI) and its potential impact on the job market raises valid concerns about the necessity of a four-year degree. While some argue that the job market is becoming saturated with degree holders, others point out that a college education still correlates with higher lifetime earnings.
Does a Four-Year College Degree Still Make Sense?
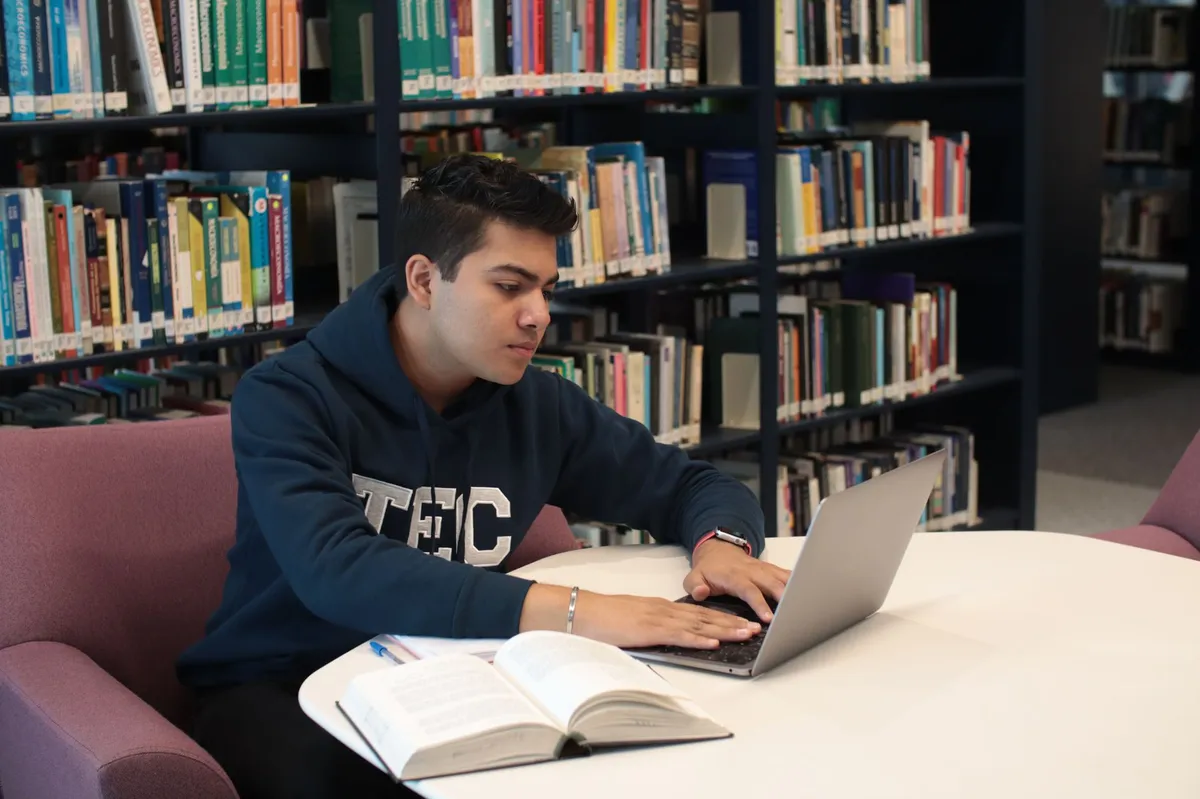
Despite the changing educational landscape, a college degree can still provide a significant return on investment. Codispoti emphasizes that while the ROI has shifted, a degree generally leads to higher earnings over a lifetime—about 59% more than those without a degree, according to the National Center for Education Statistics.
Choosing Wisely
However, the key takeaway is that not all degrees are created equal. Van Boening cautions that while certain fields remain in high demand, others may not provide a good return on educational investment. It is essential for students to have a clear plan regarding their field of study and career path to maximize the benefits of their education.
Key Takeaways
- Start saving early: Begin contributions to a 529 plan as soon as possible, ideally at birth.
- Prioritize retirement: Ensure you are saving adequately for retirement before allocating funds to college savings.
- Explore options for excess funds: Utilize excess 529 funds for other family members or roll over to a Roth IRA.
- Stay informed on legislation: Be aware of potential changes in 529 plan rules that may provide additional flexibility.
- Consider all pathways: Evaluate vocational paths and alternative education options alongside traditional college degrees.
Frequently Asked Questions
When is the best time to start saving for college?
The best time to start saving for college is as early as possible, ideally when your child is born. Early contributions allow the investment to grow over time, maximizing the benefits of compounding interest. Financial experts recommend setting a clear savings goal to determine how much you should contribute monthly or annually.
What can I do with leftover funds in a 529 plan?
Leftover funds in a 529 plan can be transferred to another family member, utilized for graduate school, or even used for vocational training. Additionally, with recent changes under SECURE 2.0, you can roll over up to $35,000 into a Roth IRA, offering more flexibility in how you use these funds.
Will the rules for 529 plans change in the future?
While it’s difficult to predict specific future changes, the trend in legislation suggests an inclination towards increased flexibility regarding 529 plans. As educational needs evolve and alternatives to traditional college gain popularity, lawmakers may consider expanding the options for how these funds can be utilized.
Should I still plan for my child to attend college?
Despite the rising costs of education and changing job market dynamics, planning for your child to attend college remains a sound decision. However, it’s crucial to consider the specific career path and educational program to ensure a good return on investment. Exploring vocational training and other educational alternatives can also provide valuable opportunities.
Disclaimer: This content is educational and not financial advice.
Comments
Empowering Women to Take Control of Their Financial Future in Retirement
As women increasingly step into financial leadership roles, it's crucial to prepare for retirement well in advance. Here are six essential tips to ensure financial security and peace of mind during major life transitions.
Related articles
Popular in Retirement
- Understanding Trump Accounts: A New Investment Opportunity for Kids
- The Impending Crisis: Social Security Reform and Its Economic Ripple Effects
- Navigating Long-Term Care Insurance: Flexible Alternatives for a Secure Future
- Balancing AI and Employee Loyalty: A Guide for Small Business Owners
- Navigating Retirement: Overcoming Doubts and Embracing Change