Navigating the Balance Between College Costs and Retirement Planning
As families approach the dual financial responsibilities of funding college and preparing for retirement, key decisions emerge. This guide explores the implications of upsizing a home in light of looming tuition costs, offering insights from financial experts.
As American families grapple with the daunting realities of college tuition and retirement planning, the delicate balance between providing for children’s education and securing one’s financial future becomes increasingly complex. For many, the dream of upsizing to a larger home to accommodate growing teenagers can feel like a pressing necessity, especially for those with substantial savings. However, as one couple with almost $4 million in assets considers their options, financial advisors are urging caution and thoughtful planning.
At the heart of this dilemma lies the question of whether to invest in a larger home before entering retirement. This couple, aged 53 and 54, has saved diligently for their future, with $3.2 million earmarked for retirement and an additional $800,000 from a family inheritance set aside for educational expenses. With college costs looming large and their youngest child still eight years away from graduation, they are contemplating whether the benefits of a bigger house outweigh the potential financial risks.
The Financial Landscape of College Tuition and Retirement
Understanding the financial implications of both college tuition and retirement planning is crucial. The average cost of attending a four-year private college in the U.S. has reached about $60,920 per year, a figure that can easily escalate when factoring in housing and living expenses. For families with multiple children, these costs can compound significantly, leading to potential financial strain.
Understanding Your College Savings
An $800,000 college fund may seem substantial, but with three children approaching college age, each could require an average of $266,000 to cover tuition and fees for four years. While this amount exceeds the average 529 college savings account balance of just over $34,000, it is essential to account for the reality that few students pay full price due to financial aid opportunities and potential scholarships. Nevertheless, the risk of underestimating future college expenses remains a critical concern.
Retirement Readiness
On the retirement side, the couple’s nest egg appears robust. Financial advisors suggest that if their investments yield an average annual return of about 9%, they could potentially double their savings over the next eight years. This projection, known as the Rule of 72, indicates that their retirement accounts could provide a comfortable annual income, especially when combined with Social Security benefits. However, this optimistic outlook must be tempered with a realistic assessment of future living expenses and market fluctuations.
The Risks of Upsizing: Weighing the Costs
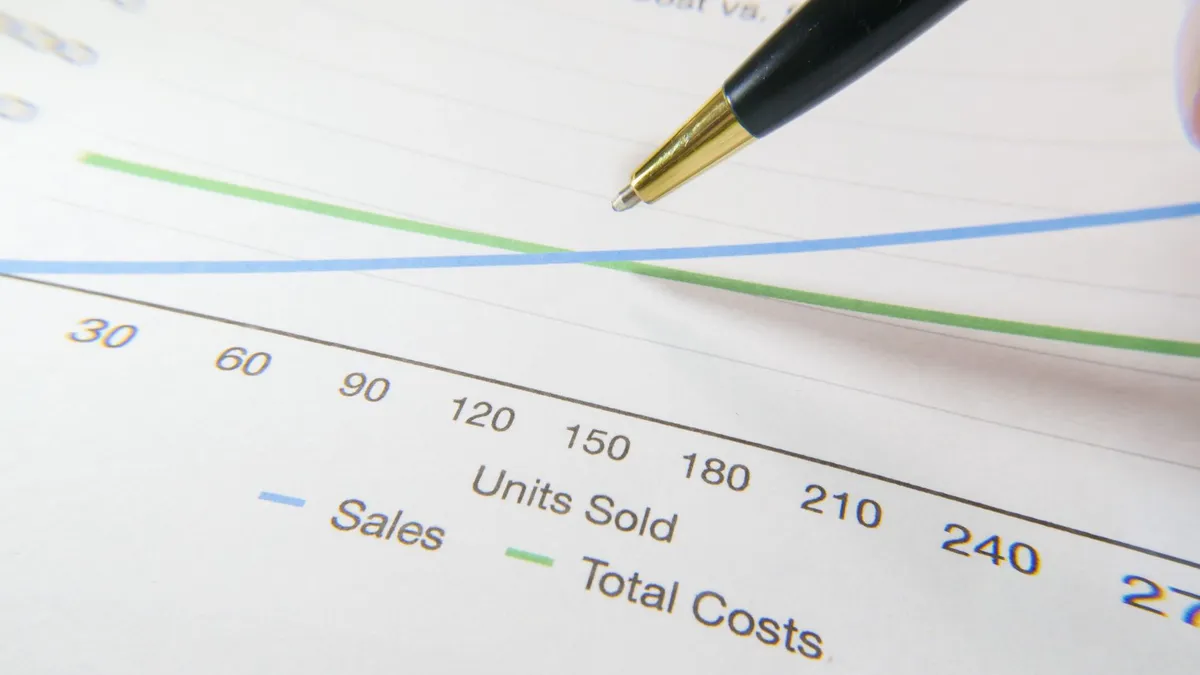
While the desire to upsize is understandable, it is essential to consider the financial implications of such a move. A larger home often entails not just a higher mortgage payment but also increased property taxes, insurance, and maintenance costs. As financial advisor Michael McSweeney points out, the couple must evaluate whether their need for more space justifies the potential for heightened financial strain.
The Hidden Costs of Homeownership
- Higher Mortgage Payments: Upsizing could triple their current mortgage payments, significantly impacting their cash flow.
- Increased Property Taxes: A larger home typically comes with higher property taxes, which can add thousands to annual costs.
- Insurance and Utility Costs: Bigger homes require more insurance coverage and incur higher utility expenses.
- Maintenance and Furnishing: More space means more upkeep and potentially costly renovations or furnishings.
Alternatives to Buying a Bigger Home
Before making a significant financial commitment, the couple should explore alternatives that can provide greater comfort without the heavy financial burden of a new mortgage. One viable option is renovating their current home to better meet their family’s needs.
Renovating vs. Upsizing
By utilizing a home equity line of credit (HELOC), they can access the equity they’ve built over the years to fund renovations. Upgrades such as finishing a basement, remodeling a kitchen, or expanding living spaces can enhance their current home’s functionality. This approach allows the family to enjoy their existing home while keeping their financial options open for retirement.
Tax Considerations
However, the couple must also be aware of the potential tax implications of their home equity and any renovations. If they decide to sell their home after living in it for many years, they may face capital gains taxes, especially if their gains exceed the $500,000 tax-free exclusion for married couples. Documenting renovation costs can help offset future tax liabilities by increasing the home’s cost basis.
Making the Right Decision for Your Family
Ultimately, the decision to upsize or renovate hinges on individual family dynamics and financial goals. While a larger home may seem appealing, it’s crucial to assess whether the added costs align with their long-term financial strategy. As financial advisor Christopher Walsh emphasizes, the couple’s past prudent decisions have led them to a solid financial position, and abandoning a successful strategy just before retirement may not be wise.
The Importance of Flexibility
Maintaining flexibility in financial planning allows them to adapt to changing circumstances, whether that means addressing unexpected college expenses or potential shifts in retirement income needs. By opting to renovate and stay in their current home, they can enjoy the benefits of increased space while preserving funds for retirement and college expenses.
Key Takeaways
- Consider the total cost of homeownership, including property taxes and maintenance, before upsizing.
- Explore renovation options to improve your current home without taking on a new mortgage.
- Keep a close eye on college expenses, especially when planning for multiple children.
- Maintain flexibility in your financial strategy to adapt to changing needs as retirement approaches.
- Document home improvements to help with future tax implications if you decide to sell.
Frequently Asked Questions
What should I prioritize: saving for college or retirement?
Both saving for college and retirement are essential, but prioritize retirement savings first. Your retirement is a long-term need and funding your future should come before financing your child's education. However, maintaining a balance is crucial; consider using a 529 plan to save for education while ensuring you are also contributing to your retirement accounts.
How can I assess if I can afford to upsize my home?
Evaluate your current financial situation by calculating your total monthly expenses, including the potential new mortgage, property taxes, and associated costs. Consider your long-term financial goals, and consult with a financial advisor to ensure your decision aligns with your overall retirement strategy.
What are the benefits of renovating my current home instead of moving?
Renovating your home allows you to create the space you need without the financial strain of upsizing. It can also be a more cost-effective solution, as you can use equity from your current home to fund improvements. This option can preserve your financial flexibility and potentially increase your home's value.
How can I prepare for unexpected college expenses?
Start by creating a comprehensive budget that includes all potential college-related expenses, such as tuition, housing, and living costs. Establish an emergency fund specifically for educational expenses, and consider discussing financial aid options with your children to ensure they are prepared to navigate the costs of higher education.
Disclaimer: This content is educational and not financial advice.
Comments
The 401(k)-Rich and Cash-Poor Retirement Trap: What You Need to Know
Many retirees face the risk of being cash poor despite having substantial 401(k) assets. This article explores the dangers of this scenario, offers strategies to mitigate risks, and highlights the importance of cash reserves.
Related articles
Popular in Retirement
- Understanding Trump Accounts: A New Investment Opportunity for Kids
- The Impending Crisis: Social Security Reform and Its Economic Ripple Effects
- Navigating Long-Term Care Insurance: Flexible Alternatives for a Secure Future
- Balancing AI and Employee Loyalty: A Guide for Small Business Owners
- Navigating Retirement: Overcoming Doubts and Embracing Change