Is Moving to a Low-Tax State for Retirement Worth It?
Relocating to a state with lower taxes can seem appealing for retirees, but this decision often comes with hidden costs. This article explores the factors to consider before making such a move.
As the golden years approach, many retirees contemplate a significant life change: moving to a low-tax state. The allure of states like Florida, Texas, and Nevada, which boast no state income tax, can be tempting for those seeking to maximize their retirement savings. However, the reality is that the financial implications of such a move can be more complex than they appear on the surface. Before packing up and leaving the familiarity of home, it's essential to fully understand what relocating might cost you in the long run.
For those who have spent decades building their nest eggs, the prospect of retaining more of that wealth through lower taxes is appealing. Yet, as financial advisors have observed, the actual savings realized from moving to a low-tax state often don't measure up to expectations. Let’s delve into the various factors that can impact this decision, from tax implications to emotional costs.
Understanding the Tax Landscape
When evaluating the financial benefits of moving to a low-tax state, it's crucial to consider the current tax laws. Recent changes in federal legislation have altered the landscape significantly.
The SALT Deduction
The state and local tax (SALT) deduction, which allows taxpayers to deduct certain taxes paid to state and local governments, plays a vital role in this discussion. The higher cap on this deduction and the introduction of new benefits for older taxpayers have reduced the federal tax burden for many retirees. For instance, the federal estate tax exemption has risen to approximately $15 million per individual, easing the tax pressure on affluent households. This narrowing gap means that the financial advantage of moving may not be as substantial as it once seemed.
Calculating Moving Costs
While the promise of lower taxes can be attractive, many potential movers often overlook the substantial one-time costs associated with relocating. These expenses can add up quickly and may negate any anticipated tax savings.
- Real Estate Commissions: Selling a house typically incurs a 5-6% commission.
- Closing Costs: These can easily reach several thousand dollars.
- Moving Expenses: Hiring movers, packing, and transportation fees can range from $2,000 to $10,000.
- Repairs and Renovations: Preparing a home for sale can cost thousands more.
- Temporary Housing: If there’s a gap between selling and buying, hotel stays can add to the overall cost.
For example, if a couple saves $6,000 annually by moving, but incurs $60,000 in moving costs, it could take a decade just to break even. This stark reality is essential to consider before making the leap.
The Emotional Cost of Relocation
Beyond financial implications, the emotional toll of moving can be significant. Leaving behind family, friends, and a familiar support network can lead to feelings of isolation.
The Importance of Community
Many retirees find that proximity to family plays a crucial role in their happiness and well-being. Missing out on birthdays, family gatherings, and other significant life events can lead to unanticipated travel costs and emotional strain. The cost of airfare and accommodations for frequent visits can quickly accumulate, further diminishing any financial savings from relocating.
Healthcare Considerations
Healthcare needs can also complicate the decision to move. Building a new network of doctors and specialists takes time and can be challenging, especially for retirees with chronic health conditions. Establishing trust with a new healthcare provider may not be easy, and the process of finding a reliable physician could take months. This continuity of care, especially for those with existing health conditions, is a factor that should not be underestimated.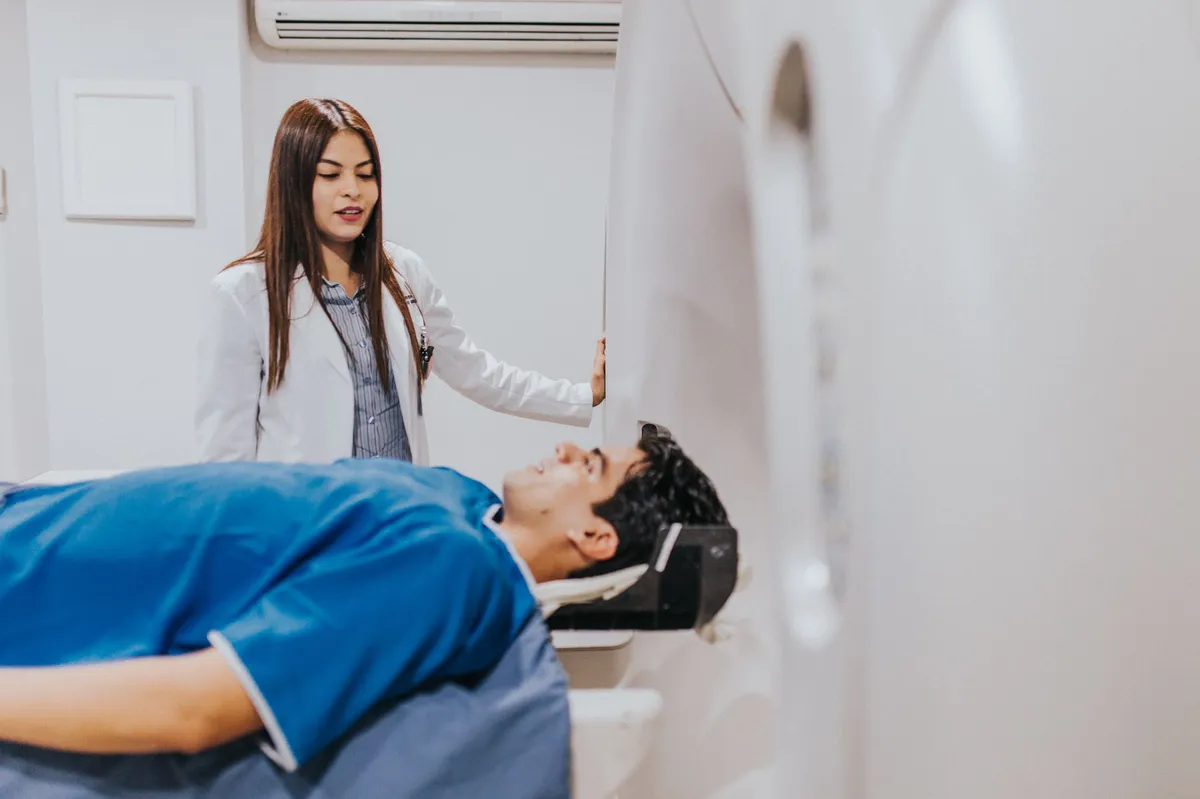
Alternative Strategies for Tax Savings
Interestingly, moving isn’t the only way to reduce tax burdens in retirement. There are numerous tax strategies that can be employed without the need for relocation.
Tax Planning Strategies
Some effective strategies include:
- Roth Conversions: Timing conversions to lower-income years can minimize tax impacts.
- Strategic Withdrawals: Managing withdrawals from retirement accounts can help mitigate tax liabilities.
- Charitable Contributions: Donating appreciated assets can yield tax benefits while supporting causes you care about.
- Social Security Timing: Deciding when to begin Social Security benefits can significantly affect overall tax liability.
These strategies can allow retirees to remain in their current homes while optimizing their tax situations.
When Moving Makes Sense
Despite the potential drawbacks, there are circumstances where relocating can be beneficial. For some individuals, factors such as affordable healthcare, housing costs that align better with their budgets, or proximity to family already living in the new state can justify the move.
Conducting a Comprehensive Analysis
It’s vital to run the numbers before making a decision. Ask yourself how much you would save each year after taxes, the total moving costs, and how long it would take to break even. Additionally, consider how often you would travel back to visit family and whether tax planning could yield similar benefits without relocating. The answers to these questions often provide clarity on whether moving is the right decision.
Key Takeaways
- Moving to a low-tax state can involve unexpected costs that may outweigh tax savings.
- One-time moving expenses can add up to tens of thousands of dollars.
- Emotional factors, such as distance from family and healthcare needs, should be considered.
- Tax planning strategies can provide savings without the need for relocation.
- Conduct a thorough analysis before deciding to move for tax reasons.
Frequently Asked Questions
Is it really worth moving to a low-tax state?
The decision to move to a low-tax state can be nuanced. While the potential for lower taxes is appealing, the accompanying costs—both financial and emotional—must be carefully weighed. It's essential to run a full analysis of your unique situation, considering all aspects of the move.
What are some common costs associated with moving for retirement?
Common costs include real estate commissions, closing costs, moving expenses, temporary housing, and the potential need for repairs to a new home. These costs can accumulate quickly, making it critical to factor them into your decision-making process.
Can I save on taxes without moving?
Yes, there are several strategies to save on taxes without relocating. Options include Roth conversions, strategic withdrawals from retirement accounts, and charitable giving. Consulting with a financial advisor can help you identify the best approach for your situation.
What emotional factors should I consider when moving?
Emotional factors, such as distance from family, support networks, and continuity of care with healthcare providers, play a significant role in the decision to move. These factors can impact your overall well-being and should not be overlooked when considering relocation.
This content is for educational purposes only and is not intended as financial advice.
Comments
Why More Retirees Are Choosing Delaware Over Florida
Delaware is gaining popularity among retirees, outpacing Florida with unique tax benefits and lifestyle perks. Discover what this means for your retirement planning.
Related articles
Popular in Retirement
- Understanding Trump Accounts: A New Investment Opportunity for Kids
- The Impending Crisis: Social Security Reform and Its Economic Ripple Effects
- Navigating Long-Term Care Insurance: Flexible Alternatives for a Secure Future
- Balancing AI and Employee Loyalty: A Guide for Small Business Owners
- Navigating Retirement: Overcoming Doubts and Embracing Change