Avoiding Retirement Pitfalls: 5 Mistakes Boomers Make with Their Nest Eggs
Many American boomers have worked hard to build their retirement savings, but common mistakes can jeopardize their financial security. This article explores critical missteps and offers actionable advice to help you safeguard your nest egg.
As many baby boomers approach retirement age, the excitement of stepping into a new chapter of life can be overshadowed by the fear of financial insecurity. Despite years of diligent saving and strategic investing, many find themselves at risk of outliving their resources. This risk often stems from a series of common financial missteps that can erode even the most robust nest eggs. Understanding these pitfalls can empower retirees to safeguard their savings and enjoy a financially secure future.
In this article, we will explore five prevalent mistakes that boomers make, along with practical strategies to mitigate these risks. From planning for long-term care to diversifying investments and safeguarding against scams, being proactive can help ensure that your retirement years are as enjoyable as you envisioned.
Avoiding Long-Term Care Planning
One of the most significant oversights in retirement planning is neglecting long-term care insurance. As we age, the likelihood of requiring assistance with daily activities increases, and the costs associated with in-home care or nursing facilities can be astronomical.
Understanding Long-Term Care Costs
Without proper insurance, the financial burden of long-term care can quickly deplete your retirement savings. According to industry experts, the average cost for a private room in a nursing home can exceed $100,000 per year, and even in-home care can run as high as $50,000 annually. This can consume a considerable portion of your savings, potentially leaving your surviving spouse with limited resources.
Choosing the Right Policy
When selecting long-term care insurance, consider factors like the policy's benefit amount, inflation protection, and coverage options. Hybrid policies that combine life insurance with long-term care benefits can offer flexibility and security. Consulting with a specialized insurance broker can help you navigate your options and find a plan that aligns with your needs.
Ignoring Alternative Assets
Many retirees stick to traditional investments like stocks and bonds, often overlooking the potential benefits of alternative assets. In a volatile market, alternative investments—such as real estate, fine art, and even cryptocurrency—can provide diversification and reduce overall portfolio risk.
Why Diversification Matters
A well-diversified portfolio can help shield your savings from market downturns. For instance, investing in real estate can yield rental income and potential appreciation, while fine art can serve as a hedge against inflation. Platforms like Arrived allow investors to participate in real estate with minimal hassle, enabling you to earn passive income without the burdens of property management.
Getting Started with Alternatives
If you're interested in alternative investments, consider services that offer access to private market opportunities. Companies like Willow Wealth provide platforms for investing in diverse assets, allowing you to start with relatively low amounts and benefit from professional management.
Falling Victim to Scams
As technology advances, so do the tactics used by fraudsters. Older Americans are particularly vulnerable to increasingly sophisticated scams, including identity theft and internet fraud. In fact, the Federal Trade Commission reported that older adults lost approximately $352 million to scams in just one year.
Recognizing and Preventing Scams
Scams often take the form of phishing emails, fake phone calls, or even voice cloning technologies that impersonate family members in distress. To protect yourself, always verify the identity of callers, especially if they claim to be relatives in need of urgent assistance. Implementing a family passphrase can provide an added layer of security and using services like Aura can help monitor your personal information across the web.
Investing in Protection
Consider subscribing to identity protection services that offer monitoring, alerts, and insurance coverage against identity theft losses. These services can provide peace of mind in an increasingly complex digital landscape.
Neglecting an Emergency Fund
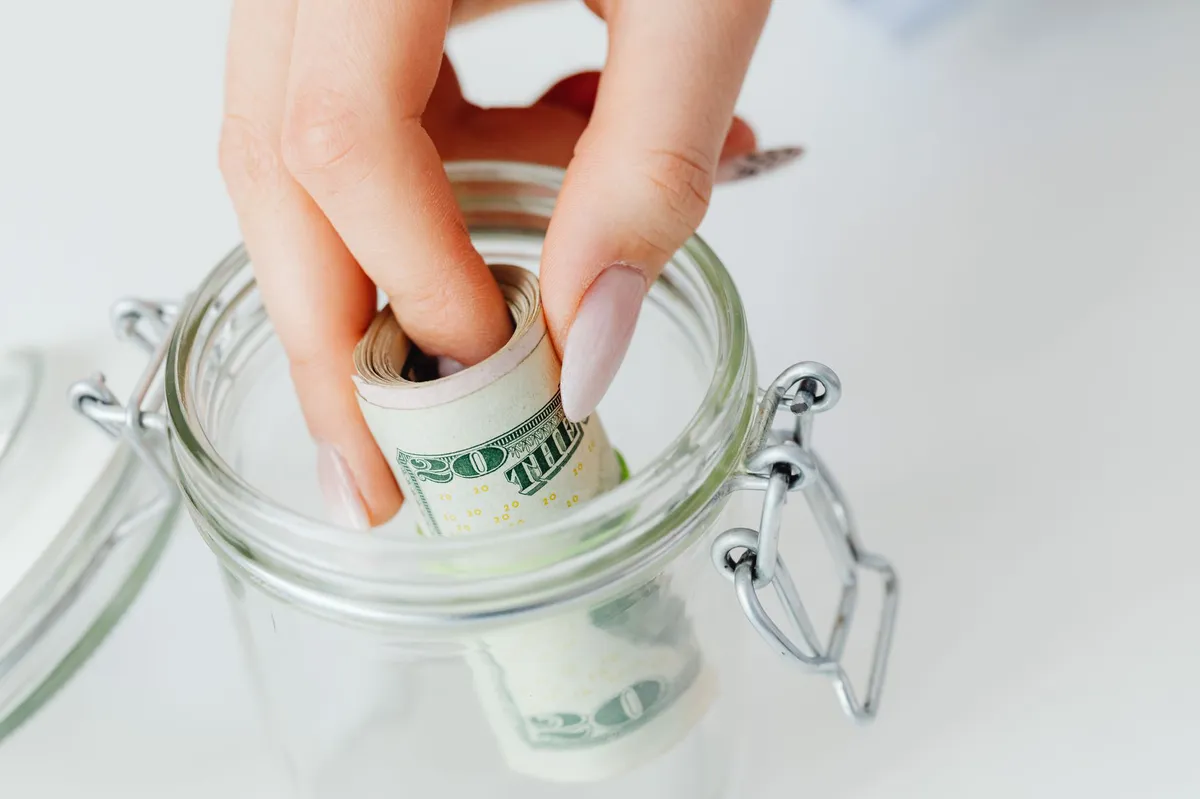
While it’s crucial to focus on your retirement savings, neglecting to maintain a healthy emergency fund can jeopardize your financial security. Unexpected expenses, such as medical emergencies or home repairs, can arise, forcing you to tap into your retirement accounts prematurely.
Building a Robust Emergency Fund
Financial advisors generally recommend having three to six months' worth of living expenses saved in an easily accessible high-yield account. For instance, a Wealthfront Cash Account offers competitive interest rates and allows for quick access to your funds, making it an excellent option for emergency savings.
Preparing for the Unexpected
Being prepared for unforeseen circumstances can help you avoid financial strain and ensure that your retirement savings remain intact. Keep your emergency fund separate from your long-term investments to ensure that you don’t unintentionally dip into your retirement savings during a market downturn.
Key Takeaways
- Plan for long-term care: Secure long-term care insurance to protect your savings from high healthcare costs.
- Diversify your investments: Consider alternative assets like real estate or fine art to insulate your portfolio.
- Stay vigilant against scams: Regularly monitor your personal information and remain cautious about unsolicited communications.
- Maintain an emergency fund: Set aside three to six months’ worth of expenses in a high-yield account to cover unexpected costs.
- Consult professionals: Work with financial advisors and insurance brokers to ensure you’re making informed decisions.
Frequently Asked Questions
What is long-term care insurance, and do I really need it?
Long-term care insurance is designed to cover services that assist individuals with daily activities, such as bathing, dressing, and eating, especially as they age. It's crucial because Medicare typically does not cover these long-term services, which can lead to significant out-of-pocket expenses. If you anticipate needing assistance in the future, securing this insurance can help protect your savings and ensure you have choices when it comes to care.
How can I diversify my investments effectively?
Diversifying your investments involves spreading your money across different asset classes to reduce risk. You can achieve this by incorporating alternative investments like real estate, commodities, or private equity into your portfolio. Platforms that specialize in these areas can provide access to opportunities that may not be available through traditional investment avenues.
What should I do if I suspect I’m being scammed?
If you suspect a scam, it’s essential to remain calm and verify the information before taking any action. Consider reaching out to the individual directly using a known contact method instead of responding to the suspicious communication. You can also report the scam to local authorities or consumer protection agencies, which can help prevent others from falling victim.
How much should I keep in my emergency fund?
A general guideline is to save three to six months’ worth of living expenses in your emergency fund. This amount can vary based on your individual circumstances, such as job stability and health needs. Aim for a high-yield account where your funds can earn interest while remaining accessible.
Comments
Understanding Financial Independence: The Key to Smart Retirement Planning
Financial independence and retirement are often confused, but understanding their differences is crucial for effective financial planning. Here’s why clarity matters and how to navigate your path wisely.
Related articles
Popular in Retirement
- Understanding Trump Accounts: A New Investment Opportunity for Kids
- The Impending Crisis: Social Security Reform and Its Economic Ripple Effects
- Navigating Long-Term Care Insurance: Flexible Alternatives for a Secure Future
- Balancing AI and Employee Loyalty: A Guide for Small Business Owners
- Navigating Retirement: Overcoming Doubts and Embracing Change